Retirement Savings and Investments
16 Roth IRA and Roth Conversion Mistakes That Cost You in Taxes
A Roth conversion can raise your Medicare premiums two years later. Every mistake on this list comes with a solution.
How you invest, spend money, buy insurance, donate to charities, fund education, and more will impact how much you pay in taxes now, and into the future. Learn to minimize what you pay the government.
Make choices to save into the right savings vehicles. Opt for pre-tax savings (traditional, SEP & Simple IRAs, 401ks, 403bs, 457s, 529s, HSAs, etc…) where you don’t pay taxes on the money you invest until you withdraw the funds in the future or after-tax savings (Roth IRAs and 401ks) are when you save money that has already been taxed.
You also want to consider how you can manipulate both income and spending to optimize your tax bracket.
A Roth conversion can raise your Medicare premiums two years later. Every mistake on this list comes with a solution.
Two CFP® professionals answer real questions on Roth conversion timing, the pro rata rule, and avoiding surprise Medicare or ACA costs.
We cover 8 creative tax strategies, plus the retirement planning approach that can save you more money.
After 50, you can contribute up to $32,500 to a 401(k) and $8,600 to an IRA in 2026. Here’s how catch-up limits work at every age.
Paying taxes in retirement means managing income streams, quarterly deadlines, and the IRS safe harbor, without an employer doing it for you.
Think you qualify for the 0% capital gains tax rate? Your other income may have already eaten that space. Here’s why, plus the 2026 brackets.
Retirees often pay more in taxes than they expect. Here’s how to plan withdrawal sequencing, Roth conversions, and RMDs for a lower bill.
A market drop lowers what you’ll owe on a Roth conversion. Learn how to turn a portfolio pullback into a long-term tax win.
Are you “lucky” enough to have to worry about #3? Did you remember #5? Explore all 10 tips on this tax season checklist.
Florida, Wyoming, and South Dakota are among the most tax-friendly states for retirees. Find out how all 50 states compare.
Most TCJA provisions are now permanent, but your bracket thresholds, deductions, and credits still changed for 2026. Here’s what’s different.
Learn how deductions affect Roth conversions and when income can be converted without triggering federal tax. Tips for smarter Roth planning.
Learn the pros and cons of different Roth conversion timing strategies and how to choose the right approach for your retirement plan.
These 13 year-end tax tips for retirement will help you minimize your 2025 taxes and reduce future tax bills.
Asset location is an important concept if you are trying to save and build wealth. Explore ways to locate funds to minimize taxes.
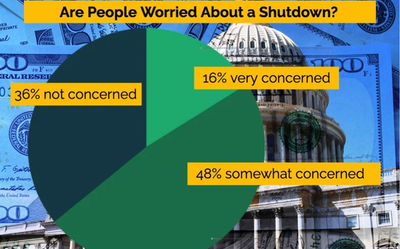
Boldin survey reveals most Americans worry a government shutdown and also the threat to ACA subsidies and retirement confidence.
Want to retire in your 50s and withdraw from savings? You need to understand the Roth 5 year rules to avoid penalties.
We’ve made the OBBBA tax updates in the Planner. Learn more about what’s changed and discover opportunities to optimize your tax planning.
Explore 7 key provisions in (or consequences of) the One Big Beautiful Bill Act (OBBBA) — and what they could mean for your retirement.
Roth conversions are a powerful tax planning strategy, but how do retirement savers actually use them? A recent survey of Boldin subscribers reveals that users…
Discover the opportunities and limits of modeling your Roth conversion opportunities and get 6 tips for doing better.
QCDs are a way to help great causes and those in need, but they are also a way to manage your tax exposure and avoid unpleasant surprises.
Yes. You might pay taxes on Social Security. Learn what to expect (federal, state and work penalties) and explore ways to reduce the expense.
Gain valuable insights into common tax terms and some of the most popular strategies for reducing what you pay.
Take financial wellness into your own hands and do it yourself retirement planning: easy, comprehensive, reliable.