Taxes
Year-End Tax Planning: 12 Moves to Make Before Dec. 31
Year-end tax planning for 2026: Roth conversions, RMDs, charitable gifts, and the 0% capital gains rate retirees can still use before Dec. 31.
Gratitude feeds an abundance mindset and more patient money choices. Here’s what the research shows and how to bring both into your financial plan.
Year-end tax planning for 2026: Roth conversions, RMDs, charitable gifts, and the 0% capital gains rate retirees can still use before Dec. 31.
Talking about money with family gets easier with a plan. These 12 tips cover timing, shared values, inheritance, and the topics most families face.
Financial success doesn’t take millions or fancy strategies. Here’s a simple nine-step recipe, from setting goals to sharing with the people you love.
Test 20 retirement scenarios, from retiring early and claiming Social Security at 70 to a market crash or long-term care, and see how each changes your plan.
Retiring in 10 years starts with a savings target and a yearly number. Here are 17 moves for your last working decade, with 2026 and 2027 limits.
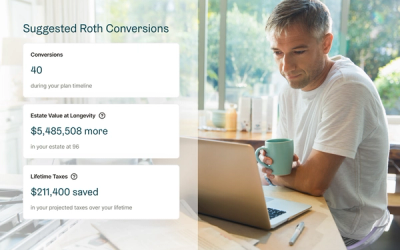
Roth conversion software shows how much to convert each year and what it does to your taxes. Here’s how the Roth Conversion Explorer in the Boldin Planner works…
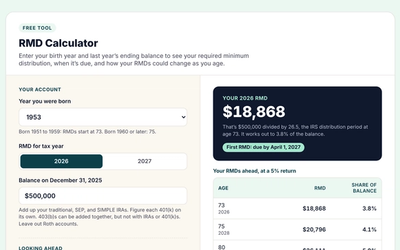
Find your required minimum distribution with our free RMD calculator, see when it’s due, and check the IRS table for 2026 and 2027.
Retirement ideas across eight areas, from hobbies and travel to part-time work and volunteering, plus how to pick the ones that fit your life and budget.
The best way to plan for your future starts with imagining it. Try these 8 research-backed ways to picture your future self and build a better plan.
Retirement wishes for coworkers, bosses, friends, and family, from funny to heartfelt, plus what to write when retirement wasn’t their choice.
A year-end financial checklist for retirees in deadline order: Medicare open enrollment, RMDs, Roth conversions, FSA balances, and the 2027 limits.
The traditional order of withdrawals in retirement is taxable accounts first, then tax-deferred accounts such as 401(k)s and traditional IRAs, then Roth account…
A QLAC turns part of your IRA or 401(k) into guaranteed income that can start as late as 85 and lowers your RMDs. Weigh the pros and cons.
Weigh the pros and cons of annuities: guaranteed income and tax deferral against fees, surrender charges, and inflation. See who an annuity fits.
Long-term capital gains are taxed at 0%, 15%, or 20%. See the 2026 and 2027 brackets by filing status and how other income pushes your rate higher.
See how much a tax-free Roth conversion can cover in 2026 and 2027, how the senior deduction adds room, and what can still cost you.
See the 2026 tax brackets for the return you file in 2027, plus the new 2027 brackets, standard deductions, and the extra deductions at 65 and older.
A market downturn lets you convert the same shares to a Roth for less taxable income. See the benefits, risks, and how much to convert in 2026 and 2027.
A Roth conversion moves pretax savings into a Roth IRA. You pay tax now, and withdrawals are tax-free later. See how it works and when it pays.
Retirement tax planning comes down to which accounts you tap, when, and how much. Here are 9 strategies, updated for 2026 and the $6,000 senior deduction.
What to gather and what to check before you file your 2026 return, from the senior deduction and RMDs to Roth conversions, QCDs, and Form 8606.
Delaying Social Security, a bond ladder, and Roth or IRA savings can beat an annuity for retirement income. Compare costs, taxes, and when an annuity fits.
The median family keeps $8,200 in bank accounts and $44,200 in total financial assets. See savings by age, for the middle class, and home equity.
The 2026 midterms put Democrats in control of Congress. Here’s what that could mean for Social Security, taxes, healthcare, and Roth conversions.
Take financial wellness into your own hands and do it yourself retirement planning: easy, comprehensive, reliable.