Retirement Planning
Financial Literacy Quiz: Can You Beat the P-Fin 8 Average?
Take the 8-question P-Fin financial literacy quiz. Only 15% of Americans got 7 or 8 right. See how you score and which gaps cost the most.
Your retirement plan is a roadmap to your future, but like all plans, it is likely to evolve and change over time.
The economy will not behave exactly as you have anticipated and your own life and goals will also change over time.
And, the best retirement planning goes way beyond your savings and investments. Numerous other factors like Social Security, when you stop work, your longevity, home equity, debt, taxes, income sources, inflation, spending, healthcare costs, lifestyle choices, and more may actually represent greater value or be more important than your savings with regards to your overall financial wellness.
Take the 8-question P-Fin financial literacy quiz. Only 15% of Americans got 7 or 8 right. See how you score and which gaps cost the most.
Risk comprehension is the weakest financial literacy domain in 2026, and age doesn’t fix it. See why six in 10 Americans struggle with financial decisions.
Retiring early means funding the years before 59½, Social Security, and Medicare. See how to price those years, save for them, and test your plan.
Retirement planning tools compared: full planners, free calculators, trackers, and advisor software, on cost and what each does best.
When tuition stops, it frees up $30,000 to $80,000 a year. Most households don’t have a plan for that money. Here’s how to put it to work.
Some 44% of Americans seriously consider retiring abroad. Greece ranked #1 in 2026. See costs, visa requirements, and where demand is going.
A retirement plan isn’t about restriction. It’s what turns limited resources into real confidence. Here’s why the constraint is the point.
Morningstar puts the safe withdrawal rate at 3.9%, but flexible strategies can push it to 5.7%. Seven takeaways and what they mean for you.
Retirement planning for couples means one plan for two lives. Coordinate retirement dates, Social Security, savings, taxes, and the survivor years.
She was self-employed, single, and unsure she’d saved enough. Then the Boldin Planner showed the full picture, and the answer surprised her.
Retirement planning assumes a lifespan of 79, but most Americans hope to live longer. Here’s how your plan can last as long as you do.
About 3 in 4 Americans have a financial regret. Here are the 15 retirees cite most, and how to fix each one.
Retirement spending estimates are often too low, but a retirement spending plan can change that. Here’s how to keep your money from running out.
Running out of money in retirement leaves you living on Social Security and safety-net programs. See what happens, who’s at risk, and how to avoid it.
Run the Dave Ramsey retirement calculator math at his 11% return and a lower one, then see what his 8% withdrawal rule means for your target.
Empower shows you what you own. Boldin models whether it lasts. See how they compare on planning depth, tax strategy, pricing, and advisor access.
After 50, you can contribute up to $32,500 to a 401(k) and $8,600 to an IRA in 2026. Here’s how catch-up limits work at every age.
Boldin is a retirement planner with AI, Monte Carlo, and Roth optimization. ProjectionLab is a modeling sandbox. Here’s how they compare.
Use 6–8% while you’re saving for retirement, 5–6% while you’re withdrawing. The right rate depends on your asset mix and timeline.
Most people do DIY retirement planning on their own. Here’s why a small peer group and tools you control can change everything.
Compare local retirement planners, CFPs, and fee-only advisors: what they charge and how to vet them. Plus DIY options, free or $168 a year.
Books on retirement planning, purpose, and healthy aging that Boldin readers keep recommending, plus top picks for gifts.
Paying taxes in retirement means managing income streams, quarterly deadlines, and the IRS safe harbor, without an employer doing it for you.
Most people skip retirement planning strategies with the highest payoff. Here are 5 of them, including one that’s essentially free money.
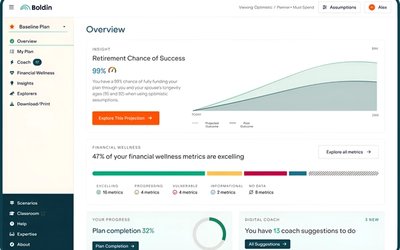
Take financial wellness into your own hands and do it yourself retirement planning: easy, comprehensive, reliable.