Retirement planning tools come in four types: full planners you run yourself, free calculators, money trackers and software built for financial advisors. A calculator gives you a quick readiness check. A full planner pulls taxes, Social Security and withdrawals into one plan you keep updating.
This guide compares Boldin with 13 other tools on cost, what each one does well and where it stops. In its 2026 review of retirement planning tools, CNBC Select named Boldin best for a complete retirement roadmap.
If you want a single number, a free calculator will get you there. If you’re weighing when to retire, when to claim Social Security and how to draw down your savings, a full planner handles that work.
How Do Retirement Planning Tools Compare?
Full planners cost $80 to $168 a year for their paid tiers, and every one in this guide offers a free version or a trial. Free calculators and government tools cost nothing, trackers run from free to about $110 a year, and advisor software comes through your advisor.
| Tool | Type | Cost | Best for | How it differs from Boldin |
|---|---|---|---|---|
| Boldin | Full planner | Free; PlannerPlus $168/yr | Ongoing plans that tie your retirement decisions together | Baseline for this guide |
| ProjectionLab | Full planner | Free; Premium $129/yr | Hands-on modeling sandbox | No AI assistant; advisors through a third-party directory |
| MaxiFi | Full planner | $149/yr after a 14-day trial | Finding one sustainable spending level | No free tier; centered on a sustainable living standard |
| Pralana | Full planner | Gold $99/yr; Online $129 first year | Spreadsheet-style detail | Gold runs in Excel; long manuals |
| OnTrajectory | Full planner | Free; Unlimited $80/yr | Light projections with an AI guide | No IRMAA tool; Roth conversions need Unlimited |
| Fidelity | Free calculator | Free; full planner needs sign-up | A quick readiness check | Tax-aware; may not fully reflect IRMAA |
| FireCalc | Free calculator | Free | Testing a withdrawal rate against history | Saves no data; no tax modeling |
| Empower | Money tracker | Free | Investment tracking and fee analysis | Free planner skips withdrawal order and Roth |
| Monarch Money | Money tracker | $99.99/yr after a 1-week trial | Budgeting and net worth | Basic forecasts; no Roth conversions |
| Quicken | Money tracker | From $6.99/mo, billed yearly | Transaction history and reports | Looks back at spending more than forward |
| RightCapital | Advisor software | Priced per advisor | Advisor-built plans | Reached through an advisor |
| eMoney | Advisor software | Through an advisor | Cash-flow plans at wealth firms | Reached through an advisor |
| MoneyGuide Pro | Advisor software | Through an advisor | Goal-based plans at advisory firms | Reached through an advisor |
| Income Lab | Advisor software | From $199/mo for firms | Income guardrails for advisor clients | No consumer tier |
Source: Vendor pricing and product pages, checked October 16, 2026. Prices are list prices and change often.
What Types of Retirement Planning Tools Are There?
Retirement planning tools differ in what they hand back to you: a full plan, a readiness estimate, a picture of your accounts today, or a plan an advisor builds for you.
| Type | What it answers | Typical cost | Examples |
|---|---|---|---|
| Full planner | When can I retire, and will my money last? | Free to about $170/yr | Boldin, ProjectionLab, MaxiFi, Pralana, OnTrajectory |
| Free calculator | Am I on track? | Free | Social Security calculators, Fidelity, FireCalc |
| Money tracker | Where is my money right now? | Free to about $110/yr | Empower, Monarch Money, Quicken |
| Advisor software | What does my advisor’s plan say? | Paid by the advisor | RightCapital, eMoney, MoneyGuide Pro, Income Lab |
Source: Vendor pricing pages, checked October 16, 2026.
The best retirement calculators answer one question from a handful of inputs, so they’re the fastest route to a first estimate.
What Does Boldin Do Best?
The Boldin Planner connects taxes, Social Security, Medicare and withdrawal strategy inside one plan. You don’t have to reconcile separate tools yourself. Here’s what it covers:
- Boldin AI answers planning questions from your actual plan data. Basic includes a limited number of questions, and PlannerPlus has no cap on conversations. On PlannerPlus, it can also draft plan updates for you to review before anything applies
- Monte Carlo scenario planning with the what-if variables you choose (PlannerPlus)
- A Retirement Chance of Success score based on 1,000 simulated market scenarios
- The Roth Conversion Explorer, with four optimization strategies (PlannerPlus)
- An Investments feature that sorts linked or manually entered holdings into seven asset classes so you can see your allocation across every account, plus what your funds cost each year and how they split across taxable, tax-deferred, and tax-free accounts (PlannerPlus)
- Tax planning that includes Medicare and IRMAA cost projections (PlannerPlus)
- A financial wellness assessment that scores your finances across a dozen metrics
- Help beyond the software: live classes, coaching and flat-fee CFP® professionals through Boldin Advisors
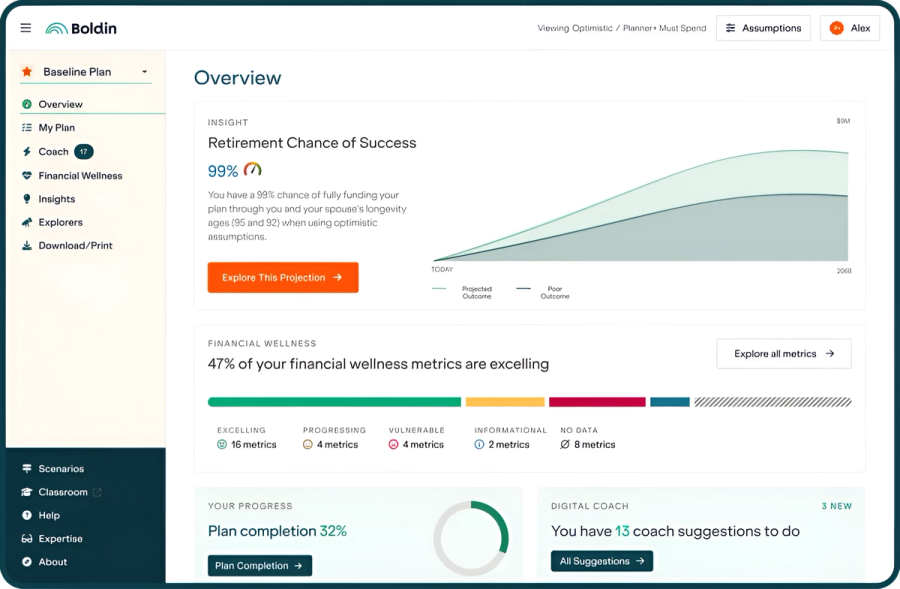
The Basic plan is free. PlannerPlus adds Monte Carlo simulation, the Roth Conversion Explorer and Boldin AI with no cap on conversations for $168 a year after a 14-day free trial.
Which Retirement Planning Tools Can You Run Yourself?
Full planners you run yourself include Boldin, ProjectionLab, MaxiFi, Pralana and OnTrajectory. Each one lets you build and update your own retirement plan without an advisor.
Boldin vs. ProjectionLab
ProjectionLab is a modeling sandbox for people who want to build every projection by hand. Its free tier includes Monte Carlo simulation and historical backtesting.
ProjectionLab has no AI assistant, and its advisor directory points you to independent advisors who use the software. Boldin AI works inside your plan, and Boldin Advisors’ CFP® professionals work from that same plan. ProjectionLab treats Social Security timing and RMDs as inputs you set. As retirement gets closer, Boldin models how they affect your tax bracket and withdrawal order.
Cost: Free; Premium is $129 a year.
Boldin vs. MaxiFi
MaxiFi and Boldin both run tax projections, Social Security claiming strategies and Monte Carlo simulations. MaxiFi builds its plan around the highest living standard it projects you can sustain. It also has Social Security and Roth optimizers and shows a Monte Carlo range.
Harry Sit of The Finance Buff names the catch: Monte Carlo always shows a wide range of outcomes. In his illustration, available spending runs anywhere from $50,000 to $200,000 a year, depending on returns. “So do I spend $50,000 or $200,000?” he asks. Boldin reports a Chance of Success for the plan you set, and lets you test changes against it. MaxiFi’s spending-first method suits people who want one number to plan around.
Cost: $149 a year after a 14-day trial, including Monte Carlo and the Roth Conversion Optimizer. There’s no free tier.
Boldin vs. Pralana
Pralana is a detailed, spreadsheet-style planner for individuals. Pralana Gold runs in Excel, and Pralana Online runs in a browser. Both editions come with long manuals.
Boldin builds that depth into a connected plan, with in-app help, a searchable help center, live and recorded classes, and Boldin AI.
Cost: Pralana Gold is $99 a year. Pralana Online is $129 for the first year and $99 a year after that.
Boldin vs. OnTrajectory
OnTrajectory is a lighter DIY projection tool for modeling income, expenses and goals. Its paid Unlimited plan adds Monte Carlo simulation and historical analysis, and it includes an AI guide.
On its Unlimited plan, OnTrajectory models Roth conversions on traditional IRAs and 401(k)s. You can ladder them over several years or fill up to a tax bracket you choose. It has no dedicated tool for IRMAA, the Medicare premium surcharge tied to your income. Boldin pairs its Roth Conversion Explorer with Medicare and IRMAA cost projections.
Cost: Free basic plan; Unlimited is $80 a year or $9 a month.
What Free Retirement Planning Tools Are There?
Free retirement planning tools include Social Security’s calculators, the Department of Labor’s savings worksheets, Fidelity’s Retirement Score and FireCalc. They work best for a first look: a benefit estimate, a readiness score, or a test of whether your savings could last.
Government Retirement Planning Tools
Federal agencies offer free tools for estimating your Social Security benefit, setting a savings goal and organizing your records.
- my Social Security shows your earnings record and personal benefit estimates at different claiming ages
- Social Security’s benefit calculators let you estimate benefits without an account
- The Department of Labor’s retirement savings worksheets help you set a savings goal and organize your records
- USAGov keeps a list of retirement planning tools, including the OPM Retirement Center for federal employees
Your Social Security estimate is one of the biggest inputs in any plan. Bring it into a full planner to test Social Security claiming strategies against the rest of your income.
Boldin vs. Fidelity’s Retirement Planning Tool
Fidelity offers free planning tools alongside its investment accounts. Its Retirement Score asks six questions and doesn’t need a login. The fuller planning experience needs a free account.
Rob Berger, reviewing Fidelity’s retirement calculator, calls it “a very easy to use tool to get a rough, and I stress rough, idea of your retirement readiness.” Fidelity’s signed-in planner calculates federal and state taxes and can model Roth conversions, though its methodology notes it may not fully reflect IRMAA. Boldin’s Roth Conversion Explorer includes an IRMAA bracket limit strategy.
Cost: Free.
Boldin vs. FireCalc
FireCalc is where many people go to sanity-check a withdrawal rate. It’s a free one-page tool that charts more than 100 possible outcomes based on historical market returns.
FireCalc doesn’t save your inputs or model taxes or Roth conversions. You can enter a Social Security start year, though you supply the benefit amount yourself. It answers a single question: could this withdrawal rate have survived past markets?
Cost: Free.
Which Tools Track Your Money Instead of Planning It?
Money trackers like Empower, Monarch Money and Quicken show where your money sits today. A few have added retirement forecasts, and those vary a lot in depth. Many people use a tracker alongside a planner.
Boldin vs. Empower
Empower, formerly Personal Capital, offers free money tools. Its strength is investment monitoring: account aggregation, fee analysis, asset allocation tracking, and net worth dashboards. Boldin’s Fund Fees view, on PlannerPlus, shows each fund’s expense ratio and yearly cost. Empower’s Retirement Fee Analyzer goes further and projects how fees shrink your balance by retirement.
Rob Berger rates it “the absolute best investment tracking app” because it does that work for free. For his own planning now that he’s semi-retired, Berger uses Boldin. Eric Rosenberg, writing at The White Coat Investor, describes Boldin as the stronger fit for action-oriented planning and Empower for investment analysis.
Empower’s free planner doesn’t model withdrawal sequencing, Roth conversions or taxes across future years. Its paid advisory service covers that ground.
Cost: The tracking and planning tools are free. Empower’s optional wealth management service starts at 0.89% of assets a year, with a $100,000 minimum. Rates drop to 0.79% above $1 million and reach 0.49% on assets over $10 million.
Boldin vs. Monarch Money
Monarch Money is a budgeting and net worth tracker. It added retirement forecasting in April 2026. The forecast takes a Social Security start age, a default withdrawal order and flat tax rates. It doesn’t model Roth conversions, optimize when to claim or project taxes bracket by bracket.
Monarch is a good fit for day-to-day spending. Boldin’s Basic plan can sit on top of it for the retirement side.
Cost: $99.99 a year or $14.99 a month after a one-week trial. There’s no free tier.
Boldin vs. Quicken
Quicken centers on tracking transactions and past spending. Boldin has budgeting tools too, and they focus on projecting spending forward. Quicken’s planners apply a flat average tax rate that you set or adjust, while Boldin projects taxes year by year.
Cost: Quicken Simplifi lists at $6.99 a month and Quicken Classic Premier at $8.99 a month, both billed yearly. First-year discounts are common.
Other Budgeting Apps
If budgeting is the main job, you have plenty of choices: YNAB, Tiller, Rocket Money, Copilot Money and PocketGuard. Credit Karma fits if your focus is credit monitoring. None of them build a retirement income plan, so pair your pick with a planner when you’re ready.
What Retirement Planning Software Do Financial Advisors Use?
RightCapital, eMoney, MoneyGuide Pro and Income Lab are sold to advisory firms and priced for them. Most people see their output only through an advisor. If your advisor uses one, you can run your own plan alongside it.
Boldin vs. RightCapital
RightCapital is planning software for financial advisors, priced per advisor per month. Reaching its tax and scenario tools means working with an advisor who uses it. Boldin gives you RightCapital-style tax and scenario modeling without an advisor.
Cost: Through an advisor; RightCapital lists plans from $149.95 per advisor per month.
Boldin vs. eMoney and MoneyGuide Pro
eMoney is an enterprise platform for wealth management firms. Its strengths are cash-flow modeling and client presentations. MoneyGuide Pro, another advisor platform, leans on goal-based probability-of-success scores.
One investor compared their CFP’s eMoney output with their own Boldin plan and found the two had converged. The difference was control. In Boldin, they could adjust Roth conversion timing and spending without waiting for an advisor to rerun the model.
Cost: Both are available only through a financial advisor.
Boldin vs. Income Lab
Income Lab is retirement income software for advisors. It focuses on spending guardrails and ongoing plan monitoring, and there’s no consumer version.
If an advisor mentioned Income Lab, you can start on Boldin’s Basic plan at no cost and decide later whether you want professional guidance on top.
Cost: From $199 a month for advisory practices.
Do You Need Software if You Have a Financial Advisor?
Software isn’t required when you work with an advisor. Running your own plan alongside one lets you test their advice between meetings and bring sharper questions to the next one. A good advisor brings experience, a wider view of your options and reassurance that’s hard to get from software alone. Advice also costs more than software, and yearly or quarterly meetings don’t cover the what-if questions that come up between them.
Your own plan also helps you judge whether a financial advisor pays off for your situation. If you want both, Boldin Advisors offers flat-fee CFP® professionals who work from your Boldin plan.
How Do You Choose a Retirement Planning Tool?
The right retirement planning tool depends on the question you’re trying to answer. To see whether you’re on track, a calculator is enough. Retirement timing, Social Security and withdrawals call for a full planner. Start with the job you need done:
- Want a full plan you control, from claiming age to withdrawal order? Boldin and the other full planners handle that
- Already using a tracker or budgeting app? Add Boldin Basic for the planning layer on top, at no cost
- Working with an advisor? Compare their plan with your own during a 14-day free trial of PlannerPlus
- Need one quick estimate? Start with Social Security’s calculators or one of the best retirement calculators
Pick the tool that matches the decision in front of you and put in your real numbers. The Boldin Planner is free to try.
Retirement Planning Tools FAQ
What are the best retirement planning tools?
The best retirement planning tools depend on the job. Full planners like Boldin, ProjectionLab, MaxiFi and Pralana build a plan that changes with your numbers. Free tools like Social Security’s calculators, Fidelity and FireCalc give a fast first read. Trackers like Empower and Monarch keep your balances in one place. CNBC Select picked Boldin for a complete retirement roadmap.
Are there free retirement planning tools?
Free retirement planning tools include Social Security’s benefit calculators, the Department of Labor’s savings worksheets, Fidelity’s planning tools, FireCalc, Empower and Boldin’s Basic plan. Free versions handle estimates and account tracking. Paid tiers add features like Monte Carlo simulation, tax projections and Roth conversion modeling.
What’s the difference between a retirement calculator and a retirement planner?
A retirement calculator answers one question, such as whether your savings could last, from a few inputs. A retirement planner holds your whole financial picture, including your tax bracket, claiming age and drawdown order, and updates as your numbers change. Calculators suit a one-off check. Use a planner for decisions you’ll revisit for years.
Is retirement planning software worth paying for?
Retirement planning software pays for itself when your plan has decisions a single estimate can’t settle: when to claim Social Security, how to time Roth conversions, how to cover healthcare before Medicare, or which accounts to draw from first. Paid tiers of the full planners in this guide cost $80 to $168 a year.
Is Boldin better than Empower?
Boldin and Empower do different jobs. Empower is a free tracker centered on investment monitoring and fee analysis. Boldin builds a retirement plan that models withdrawals, Roth conversions and taxes across future years. Many people use Empower to watch their accounts and Boldin to plan what those accounts will pay for in retirement.
Is Boldin the same as NewRetirement?
Boldin is the new name for NewRetirement. The company changed its name in September 2024, and the planner, your account and the tools carried over. Plans you built in NewRetirement are still there when you log in to Boldin, and the free Basic plan and paid PlannerPlus tier continue under the Boldin name.