Retirement Savings and Investments
Early Retirement Withdrawals: How to Avoid the 10% Penalty
Five penalty-free ways to tap your 401(k) or IRA before 59½. How SEPP, Rule of 55, Roth withdrawals, and two more actually work.
Run the Dave Ramsey retirement calculator math at his 11% return and a lower one, then see what his 8% withdrawal rule means for your target.
Five penalty-free ways to tap your 401(k) or IRA before 59½. How SEPP, Rule of 55, Roth withdrawals, and two more actually work.
Empower shows you what you own. Boldin models whether it lasts. See how they compare on planning depth, tax strategy, pricing, and advisor access.
Applying can take as little as 15 minutes. Deciding when to start matters far more, and it's hard to undo. Here's the 5-step process, plus what to weigh first.
Using ‘Atomic Habits’ to reach your financial goals — James Clear’s habit framework applied to wealth building and long-lasting confidence.
We cover 8 creative tax strategies, plus the retirement planning approach that can save you more money.
Learn how to find purpose after retirement using mindfulness, ikigai, and other research-backed strategies for feeling fulfilled again.
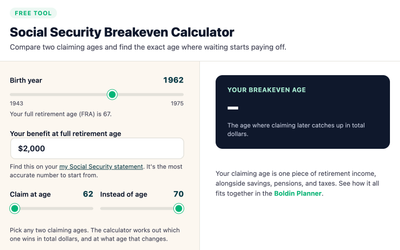
Skip the generic age-80 estimate. Find your exact Social Security breakeven age from your own birth year and benefit.
Working in retirement can boost your income and your plan. See how a job affects Social Security, Medicare, and taxes, and how to find work you want.
Social Security uses your top 35 earning years. Stop early and your projected benefit gets cut. Here’s what the math shows.
After 50, you can contribute up to $32,500 to a 401(k) and $8,600 to an IRA in 2026. Here’s how catch-up limits work at every age.
The average Social Security benefit for retired workers is $2,071 a month. Millions of retirees live on that. Here’s where to start.
Boldin is a retirement planner with AI, Monte Carlo, and Roth optimization. ProjectionLab is a modeling sandbox. Here’s how they compare.
Original Medicare vs. Medicare Advantage, Social Security timing, and the enrollment errors that follow you permanently.
Use 6–8% while you’re saving for retirement, 5–6% while you’re withdrawing. The right rate depends on your asset mix and timeline.
Most people do DIY retirement planning on their own. Here’s why a small peer group and tools you control can change everything.
Hiro Finance is gone. Compare the best alternatives, including a powerful AI tool built for smarter financial planning.
Compare local retirement planners, CFPs, and fee-only advisors: what they charge and how to vet them. Plus DIY options, free or $168 a year.
Books on retirement planning, purpose, and healthy aging that Boldin readers keep recommending, plus top picks for gifts.
Paying taxes in retirement means managing income streams, quarterly deadlines, and the IRS safe harbor, without an employer doing it for you.
Most people skip retirement planning strategies with the highest payoff. Here are 5 of them, including one that’s essentially free money.
Using ChatGPT for retirement planning? We asked ChatGPT and Boldin AI the same question: “Can I retire?” This is how they replied.
Learn how CalSavers applies to California workers and employers, including automatic Roth IRA enrollment, payroll deductions, and benefits.
What does Suze Orman say about annuities? They can offer guaranteed lifetime income, but fees, taxes, and surrender charges are real trade-offs.
Delaying Social Security to 70 can add $100,000+ in lifetime benefits. These are the planning strategies that make the biggest difference.
Take financial wellness into your own hands and do it yourself retirement planning: easy, comprehensive, reliable.