Health insurance from 62 to 65 costs $1,000 to $1,800 a month or more for a full-price benchmark Silver plan, depending on where you live. Subsidies can cut that sharply below the 400% poverty line, about $63,840 for one person on 2027 plans. Above it, you pay full price.
If you’re retiring at 62, Medicare doesn’t start for three more years, so you cover that stretch on your own. ACA rules let insurers charge a 62-year-old nearly three times what a 21-year-old pays for the same plan. If that cost isn’t in your plan, it can push back a retirement date that was otherwise within reach.
Here’s what coverage costs, what changed with ACA subsidies for 2027 plans, and how to plan the three years so they don’t derail your retirement date.
Health Insurance at 62 Can Cost Over $1,000 Per Month Without a Subsidy
ACA rules cap age rating at three times what a 21-year-old pays, and that cap applies at 64. A 62-year-old pays nearly three times as much. That often puts full-price benchmark Silver premiums between $1,000 and $1,800 a month or more, depending on where you live.
Marketplace plans price each person separately, so two 62-year-olds pay about twice the single figure before subsidies. Insurers can’t charge women and men different prices for the same plan.
What you pay at 62 depends on your coverage type, income, and location. The table uses 2026 figures as directional benchmarks until 2027 premium data is in, and your actual costs will vary.
| Coverage Type | Estimated Monthly Cost (2026) | Key Details |
|---|---|---|
| ACA Marketplace, no subsidy | $1,000–$1,800+ | Age-rated; varies by state, plan tier, and county. |
| ACA Marketplace, with subsidy | $0–$800+ | Subsidies run from 138% to 400% of the federal poverty level in most states: about $21,597 to $62,600 for one person on 2026 plans and $22,025 to $63,840 on 2027 plans. In non-expansion states, subsidies start at 100% FPL. |
| COBRA | $700–$1,800 | Full employer-plan cost + 2% admin fee; lasts 18 months in most cases. |
| Employer plan (still working) | $200–$600 | Employee share only; often the least expensive if available. |
| Spousal plan | Varies | Often the lowest-cost option if a spouse has employer coverage. |
| Private/short-term coverage | $300–$1,000+ | Flexible but often limited benefits and weaker protections than ACA plans. |
Sources: KFF Health Insurance Marketplace Calculator (2026); KFF Employer Health Benefits Survey (2025); DOL COBRA guidelines.
ACA premiums at 62 are age-rated, so they run well above what a 40-year-old pays, and the gap shows most when you don’t qualify for subsidies. To check your zip code, run your age, income, and family size through the KFF Health Insurance Marketplace Calculator, which uses current Marketplace data for your county.
The Enhanced ACA Subsidies Expired. Here’s What That Means for 2027 Coverage.
The enhanced premium tax credits that held down ACA costs from 2021 through 2025 expired at the end of 2025. Congress hasn’t renewed them for 2026 or 2027 coverage, and a House-passed extension stalled in the Senate. The subsidy cliff is back. Above 400% of the federal poverty level, you get no premium tax credit at all. That line is about $62,600 for one person on 2026 plans and $63,840 on 2027 plans. Open enrollment for 2027 plans runs from Nov. 1, 2026 to Jan. 15, 2027. Enroll by Dec. 15 for coverage that starts Jan. 1.
Below that cutoff, subsidies still exist but are smaller than they were under the temporary enhancements. Your share of the benchmark premium is higher than in 2025 at the same income. Where base premiums run high, a 62-year-old above the cutoff can face $1,200 to $1,800 or more a month for a benchmark Silver plan.
A California Health Care Foundation analysis of 2026 premiums found one Californian whose benchmark Silver premium jumped from about $554 to over $1,000 a month. The enhanced subsidies had just ended. For early retirees drawing from investment accounts, it’s now easier to push modified adjusted gross income (MAGI) over the cutoff. One high-income year can erase the whole subsidy.
That makes MAGI management matter more than it has since 2020. The strategies below show how account sequencing and income planning can keep you under the line where it makes sense.
One more change raises the stakes. Starting with 2026 tax returns, there’s no cap on paying back excess subsidies. If your MAGI comes in higher than you estimated, you repay the full difference at tax time. Update your income estimate with the Marketplace when it changes.
Your Coverage Options Before Medicare: ACA, COBRA, and Spousal Plans Compared
Most early retirees end up choosing between the ACA Marketplace, COBRA, and a spouse’s employer plan to cover the pre-Medicare years. Each path has its own costs, time limits, and eligibility rules. The right fit turns on your income, your health, and how long you need to bridge to 65.
ACA subsidies cut your premiums, depending on your income
For most people retiring at 62, ACA coverage is the most practical option. Pre-existing conditions can’t be used to deny you coverage or raise your premiums, which matters in your early sixties, when health issues become more common.
Your subsidy is based on your MAGI and household size. In most Medicaid expansion states, Marketplace subsidies are available for incomes between 138% and 400% of the federal poverty level. For a single person, that’s about $21,597 to $62,600 on 2026 plans and $22,025 to $63,840 on 2027 plans. Below the 400% line, you pay at most 10.22% of income for a benchmark plan in 2027, according to IRS Revenue Procedure 2026-26. In states that did not expand Medicaid, subsidy eligibility begins at 100% FPL, because there is no Medicaid coverage below that threshold.
The order you draw from accounts drives your MAGI. Qualified Roth IRA withdrawals don’t count toward it. Withdrawals from traditional 401(k)s and IRAs do, and so do taxable interest, dividends, capital gains, and all of your Social Security benefits, including the untaxed part. That’s why claiming Social Security at 62 can push a retiree over the cliff. If you have both Roth and pre-tax savings, drawing from Roth first and managing realized gains can keep MAGI under the thresholds that shrink or erase your subsidy. That can save several hundred dollars a month in premiums.
Below 250% FPL, you may also qualify for cost-sharing reductions on Silver plans, which reduce deductibles and out-of-pocket limits in addition to premium help.
COBRA is a bridge, and an expensive one
Leaving a job with group health coverage often lets you keep that plan for a while through COBRA. Standard COBRA lasts 18 months for the covered employee and dependents, and you pay the full cost of the plan plus up to a 2% administrative fee.
If Social Security finds you disabled before COBRA starts or within its first 60 days, coverage can extend to 29 months. You have to notify the plan within 60 days of the SSA decision and before the 18 months end. Certain second qualifying events, like the employee’s death, divorce, or a dependent aging off the plan, can extend COBRA to 36 months for spouses and dependent children.
COBRA is expensive, but Boldin’s lead educator and financial wellness coach Nancy Gates points to a few situations where it’s useful. “If you’re retiring mid-year and you’ve already met your deductible, or you’re dealing with high medical expenses and want to stay on a plan you know, COBRA can make real sense,” she says. “It’s a solid short-term option, just not a low-cost or long-term one.”
One common pattern: retire at 63, use COBRA for up to 18 months while you weigh ACA options, then move to a Marketplace plan. As a three-year solution from 62 to 65, COBRA’s full premium is hard to justify unless your employer plan costs little.
Spousal coverage is often the cheapest path
If your spouse is still employed and eligible for group coverage, joining their employer plan is often your lowest-cost option. Adding a spouse to a group plan often undercuts individual ACA pricing, even at the family rate, because the employer pays part of the premium.
Many couples structure early retirement around this. One person retires, and the other keeps working a few more years, in part for the health benefits. Price both spouses’ plans before you both leave.
Private and short-term plans offer less protection
Private plans sold outside the ACA Marketplace and short-term policies offer year-round enrollment and no income rules. Many can underwrite based on health, exclude pre-existing conditions, or cap benefits in ways ACA plans can’t.
For most early retirees, these plans make sense only as a last resort. Price them if your situation is unusual, but ACA coverage or a short stretch of COBRA tends to win on protection and long-term value.
How to Lower Your Health Insurance Cost Before 65
Two strategies do most of the work. Build a Health Savings Account (HSA) while you’re still employed, and manage your MAGI to stay in subsidy range. Together, they can cut what you pay for health insurance and out-of-pocket costs between 62 and 65 by several hundred dollars a month.
Build your HSA before you retire
If you’re still working and have a high-deductible health plan (HDHP), an HSA is a strong way to prepare for healthcare expenses in retirement. Contributions are deductible, growth is tax-free, and withdrawals for qualified medical expenses are tax-free too, a triple tax advantage. Qualified expenses include deductibles, copays, prescriptions, dental, and vision.
For 2026, the IRS HSA contribution limits are:
- $4,400 for self-only HDHP coverage
- $8,750 for family coverage
- +$1,000 catch-up for eligible individuals 55 or older by the end of the tax year who aren’t yet on Medicare
If both you and your spouse qualify for the catch-up, each of you needs a separate HSA to use it. Once you’re retired, HSA funds can cover out-of-pocket medical costs, COBRA premiums, and health insurance premiums while you’re receiving unemployment benefits. ACA Marketplace premiums are the main item an HSA can’t pay. You may still be able to keep contributing after you retire, since bronze and catastrophic Marketplace plans count as HSA-eligible coverage starting in 2026.
One timing nuance: HSA eligibility stops when you enroll in Medicare, and Part A enrollment is often retroactive for up to six months. Stop HSA contributions well before your Medicare start date to avoid excess contributions.
Keep your MAGI in subsidy range
Your ACA subsidy is calculated from your MAGI, so how you draw income from 62 to 65 matters as much as how much you spend. Traditional IRA and 401(k) withdrawals, taxable interest and dividends, and realized capital gains count toward MAGI. So do all of your Social Security benefits, including the untaxed part. Qualified Roth IRA withdrawals and the cost-basis part of a taxable-account sale don’t.
If you can cover living costs from Roth accounts or by selling assets with low gains, you may stay under key thresholds. That can qualify you for larger premium tax credits and cost-sharing reductions. It takes some up-front planning around withdrawal sequencing, and the payoff from 62 to 65 can be large.
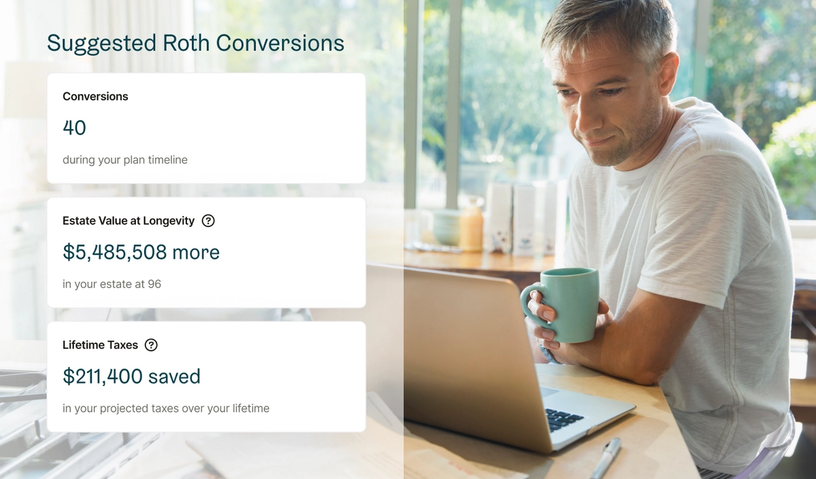
The Boldin Planner lets you try different withdrawal orders and see how they change your income and taxes each year. Use the year-by-year income and withdrawals to estimate your MAGI, add any untaxed Social Security, and compare it with the 400% line.
Retirement health is also shaped by lifestyle choices, even though they’re not a substitute for insurance. As Boldin financial wellness coach Nancy Gates notes, “Physical activity, mental stimulation, meaningful relationships, and a sense of purpose all work together to help keep healthcare costs low. The retirees who stay engaged and healthy generally spend less over time.”
When to Start Planning for Medicare Enrollment
Medicare eligibility begins at 65 for most people. Your Initial Enrollment Period (IEP) runs seven months: the three months before the month you turn 65, your birthday month, and the three months after. Miss it without qualifying employer coverage, and you may have to wait for a General Enrollment Period. You’d also pay a permanent Part B late penalty of 10% for each full 12 months you were eligible but not enrolled.
People covered by a current employer’s group plan at 65, their own or a spouse’s, can often delay Part B. They get a Special Enrollment Period when that coverage ends, with no penalty. As 65 nears, coordinate Medicare timing with any HSA contributions, since Medicare enrollment ends HSA eligibility.
Medicare.gov explains how employer coverage and COBRA interact with Medicare. Once you’re on Medicare, you can change plans each fall during Medicare’s open enrollment, Oct. 15 to Dec. 7.
How to Estimate Your Actual Health Insurance Cost at 62
Your actual cost at 62 depends on three main variables: your zip code, your household income (MAGI), and the plan tier you choose. The KFF calculator gives you the premium. The Boldin Planner shows how that cost fits with your income, taxes, and spending.
Here’s a simple three-step process:
- Estimate your MAGI for the year you plan to retire. Include any wages, pension income, traditional IRA or 401(k) withdrawals, investment income, and Social Security. Decide how much you’ll draw from Roth accounts and taxable savings.
- Run the KFF Health Insurance Marketplace Calculator for your zip code using that MAGI estimate. In under two minutes, it will show you the benchmark premium, your expected subsidy (if any), and the net monthly cost for different plan types.
- Model the same scenario in the Boldin Planner. Run the KFF calculator at three incomes: your expected MAGI, 10% below, and 10% above. Enter each premium as your pre-Medicare healthcare cost. Adjust the withdrawal order, or exclude accounts, until your withdrawals come close to that income. Saving those as separate scenarios takes PlannerPlus. Compare how your taxes and spending change in each.
The spread across those three income levels is often the difference between retiring at 62 with confidence and needing to work another year. Seeing the numbers for ages 62, 63, and 64 side by side makes the tradeoffs clearer.
Lower-Cost Alternatives: Part-Time Work and Health Sharing Ministries
Part-time work with benefits and health sharing ministries can both cut premiums for early retirees. Neither replaces a full coverage plan, and each comes with catches.
Some part-time jobs offer health coverage
Some early retirees take a part-time job for one reason: the health benefits. A few large employers, many in retail and food service, offer medical coverage to part-timers. Their rules often require 20 to 30 hours a week plus a waiting period.
These rules change. Whole Foods ended medical coverage for part-time workers under 30 hours a week starting in 2020, for example. Confirm current eligibility, hours, and waiting periods on the employer’s benefits site before you take a job for the coverage.
Health sharing ministries cost less and guarantee nothing
Healthcare sharing ministries are faith-based groups that pool member contributions to pay each other’s medical bills, outside normal insurance regulation. Monthly contributions often run below ACA premiums at older ages, and you can join year-round. That appeals to people who are healthy and focused on keeping near-term costs low.
The catch is protection. These programs aren’t insurance, have no legal duty to pay any claim, can limit sharing for pre-existing conditions, and often exclude care a regular policy covers. Before you join, review member complaints, payment history, the ministry’s finances, and its “eligible for sharing” rules.
Even if you’re considering one of these, price an ACA plan at your income and zip code before you opt out of regulated coverage.
Build a Health Insurance Budget for Ages 62 to 65
Health insurance between 62 and 65 works as a three-year budget phase with moving parts. Your premiums, subsidies, and out-of-pocket costs can change each year as your income, coverage choices, and health needs evolve. Costs continue once Medicare starts: Fidelity estimates a 65-year-old retiring in 2026 will spend $185,500 on healthcare over the rest of retirement.
To plan this window well, it helps to:
- Estimate likely premiums at different MAGI levels using the KFF calculator for each year between 62 and 65.
- Decide how you’ll sequence withdrawals from taxable, tax-deferred, and Roth accounts to stay within subsidy range when it matters most.
- Map out when you’ll transition from employer coverage or COBRA to the Marketplace, and when Medicare will take over at 65.
The Boldin Planner lets you model 62 to 65 as its own phase, with healthcare costs, income sources, and taxes in one place. Seeing those three years laid out side by side can make retiring at 62 look more within reach than a vague “big expense” suggests.
FAQ: Health Insurance in Early Retirement
How much does health insurance at 62 typically cost?
Health insurance at 62 can cost $1,000 or more a month for a full-price ACA benchmark Silver plan, depending on state, county, and plan tier. Income below about $62,600 for one person on 2026 plans, or $63,840 on 2027 plans, can qualify you for subsidies. A Marketplace subsidy calculator shows the net cost for your zip code.
Can I get health insurance at 62 if I retire before Medicare age?
You can get health insurance at 62 through the ACA Marketplace. Leaving a job with coverage is a qualifying life event that opens a 60-day special enrollment window. ACA-compliant plans can’t use pre-existing conditions to deny you coverage or charge you more.
What’s the income limit for ACA subsidies in 2026 and 2027?
ACA premium tax credits stop at 400% of the federal poverty level. That’s about $62,600 for one person and $84,600 for a couple on 2026 plans, and about $63,840 and $86,560 on 2027 plans. In Medicaid expansion states, people below about 138% of the poverty level often qualify for Medicaid instead.
Can I use my HSA to pay health insurance premiums before Medicare?
You can’t use HSA funds to pay ACA Marketplace premiums before Medicare. You can use them for COBRA premiums and for health insurance premiums while you’re receiving unemployment benefits. After you enroll in Medicare, an HSA can pay Part B, Part D, and Medicare Advantage premiums tax-free, though new contributions stop.
How long does COBRA coverage last?
Standard COBRA lasts 18 months, up to 29 or 36 months in some cases, so most people retiring at 62 can’t ride it to Medicare. Many use COBRA through the plan year, then switch to a Marketplace plan at open enrollment or when COBRA ends. Dropping COBRA early doesn’t open a special enrollment period, so time the switch.
How did the 2026 ACA changes affect health insurance costs for early retirees?
The enhanced subsidies expired, so one person earning above about $62,600 (2026) or $63,840 (2027) gets no subsidy, and excess credits are repaid in full. To stay under the line, estimate your MAGI before open enrollment, pick which accounts to draw from, and size any Roth conversion. Update your Marketplace estimate when income changes.
What happens if I miss my Medicare enrollment window at 65?
If you miss your Initial Enrollment Period at 65 without qualifying employer coverage, you may have to wait for a General Enrollment Period. You’ll also pay a permanent Part B late penalty of 10% of the standard premium for every 12 months you went without Part B. Active employer coverage at 65 often qualifies you for a Special Enrollment Period.
Is COBRA or the ACA Marketplace cheaper for someone retiring at 62?
Whether COBRA or the ACA Marketplace is cheaper at 62 depends on your income and your former employer’s plan cost. Below about 400% of the poverty level, a subsidized ACA plan tends to cost less than full-price COBRA. Above the cutoff, the costs run closer, so compare your COBRA premium against Marketplace quotes for your zip code.
How many years do I need to cover my own health insurance if I retire at 62?
If you retire at 62 and enroll in Medicare at 65, you cover three full years on your own: ages 62, 63, and 64. If you delay Medicare because you keep working or have employer coverage, the window stretches, so plan coverage around your actual Medicare start date.