You can make money in retirement by using your career skills, taking part-time or gig jobs, renting out space, or selling things you don’t need. Most of these pay between $13 and $37 an hour, based on federal wage data. Consulting in your old field pays more.
Many people plan on it. In Fidelity’s 2026 State of Retirement Planning survey, 35% of Americans said they’re thinking about gig work or side hustles as they move into retirement. Fewer follow through. In the 2026 EBRI/Greenwald Retirement Confidence Survey, 75% of workers said they expect income from work in retirement, and 27% of retirees said they have it.
Here are 14 ways to make money after retirement, what each one pays, and what extra income does to the rest of your plan.
How Much Do Retirement Side Hustles Pay?
Most retirement side hustles pay $13 to $37 an hour. Consulting pays $37 to $64, and hourly jobs like retail, pet care, and driving pay $14 to $22. The best-paying ones draw on skills you already have.
| Side hustle | Typical pay | Startup effort | Good fit if you |
|---|---|---|---|
| 1. Consulting or freelancing | $37 to $64 an hour | Low | Have a network in your old field |
| 2. Tutoring | $17 to $26 an hour | Low | Know a school subject or test well |
| 3. Teaching a skill or hobby | $17 to $30 an hour | Medium | Have a craft, art, or skill people want to learn |
| 4. Tax prep or bookkeeping | $19 to $37 an hour | Medium | Have a finance or accounting background |
| 5. Substitute teaching | $16 to $26 an hour | Medium | Like working with kids and can meet state rules |
| 6. Retail or seasonal work | $14 to $19 an hour | Low | Want set shifts and an employee discount |
| 7. Pet sitting or dog walking | $14 to $19 an hour | Low | Love animals and want to stay active |
| 8. Driving or delivery | $16 to $22 an hour | Low | Have a reliable car and know your area |
| 9. Event staff or campground host | $13 to $18 an hour | Low | Like crowds, or travel by RV |
| 10. Renting a room or your home | Depends on local rents | Medium | Have space and don’t mind guests |
| 11. Renting storage space | Depends on space and demand | Low | Have an empty garage, shed, or driveway |
| 12. Selling what you don’t need | Depends on what you sell | Low | Are downsizing or decluttering |
| 13. Research studies and surveys | A few dollars per task | Low | Want pocket money on your own schedule |
| 14. Claiming unclaimed money | Whatever you’re owed | Low | Have moved, changed jobs, or closed accounts |
Source: U.S. Bureau of Labor Statistics, Occupational Employment and Wage Statistics, May 2025. Ranges for ideas 1 to 9 show the middle half of hourly pay (25th to 75th percentile) for the closest matching job. BLS counts employees, so self-employed rates can run higher or lower.
Can Your Career Skills Earn Money in Retirement?
The highest-paying ways to earn money in retirement use what you already know. Clients pay for judgment they can’t get from a new hire.
1. Consult or Freelance in Your Old Field
Former managers, engineers, accountants, and marketers can sell their expertise by the project. Management analysts, the closest federal wage match, earn $37 to $64 an hour, and as a consultant you choose which jobs to take. Start with former employers, colleagues, and vendors, since they already know your work. Steady clients can turn consulting into a small business of your own.
2. Tutor Students or Teach Online
If you taught, worked in a technical field, or know a subject well, you can tutor. Tutors earn $17 to $26 an hour, and test prep and advanced subjects pay more. Wyzant matches tutors with students, and local schools and libraries run programs too. You can meet in person or by video.
3. Teach a Skill or Hobby
Woodworking, quilting, photography, baking, music, and languages can all turn into classes. Community centers, craft stores, and continuing-education programs hire instructors, or you can run small workshops yourself. Instructors earn $17 to $30 an hour.
4. Do Seasonal Tax Prep or Bookkeeping
Tax preparation firms hire seasonal staff from late winter through mid-April. Small businesses need help with invoices and payroll all year. Tax preparers earn $19 to $37 an hour, and bookkeepers earn $21 to $30. A finance or accounting background helps you get hired.
Which Gig and Hourly Jobs Work for Retirees?
Substitute teaching, retail shifts, pet sitting, driving, and event work all let you start fast and stop when you want. Part-time and gig jobs like these pay less than skilled work, and many let you choose when you work. Some remote jobs for seniors need only a computer.
5. Substitute Teach
Many school districts are short on substitutes. Subs earn $16 to $26 an hour, and you can accept or turn down assignments. Requirements vary by state. Some ask for a bachelor’s degree or a teaching license, and others ask for less.
6. Pick Up Retail or Seasonal Shifts
A shift at a garden center, bookstore, or hardware store pays $14 to $19 an hour and often comes with an employee discount. Holiday and summer seasons bring extra openings if you’d rather work a few months a year.
7. Pet Sit or Walk Dogs
Pet owners pay for walks, drop-in visits, and overnight stays. Apps like Rover connect sitters with clients. Animal caretakers earn $14 to $19 an hour, and sitters who book their own clients set their own rates.
8. Drive or Deliver
Shuttle, chauffeur, and medical-transport drivers earn $16 to $22 an hour. Rideshare and delivery apps let you set your own hours, but gas and wear on your car come out of what you make. Check whether your auto insurance covers paid driving before your first trip.
9. Work Events or Campgrounds
Concert venues, stadiums, theaters, and conference centers hire ushers, ticket takers, and concession staff for $13 to $18 an hour. If you travel by RV, campground host jobs trade work for a free campsite, and some pay an hourly wage on top.
What Can You Rent or Sell for Extra Income?
Your home, garage, and closets can bring in money without a set schedule. Most of the work happens up front. Bigger moves, like a reverse mortgage or a sale, tap your home equity.
10. Rent Out a Room or Your Home
A spare bedroom can earn rent from a long-term tenant or short-term guests through Airbnb or Vrbo. If you travel for part of the year, renting out your whole home can help cover the trip. Check local rules and your HOA first, since many cities limit short-term rentals.
One tax rule works in your favor. If you rent out your home for 14 days or fewer in a year, the IRS doesn’t count that rental income.
11. Rent Out Storage or Parking Space
An empty garage, shed, driveway, or closet can earn monthly rent from someone who needs storage. Neighbor works like Airbnb for storage. You list the space, set a price, and renters pay through the site.
12. Sell What You No Longer Need
Retirement, and downsizing above all, turns up furniture, tools, collectibles, and clothes you don’t use. Facebook Marketplace, eBay, and OfferUp work well for single items. Consignment shops and estate-sale companies handle larger lots for a cut of the sale. Meet local buyers in a public place, like a police station parking lot.
Where Can You Pick Up Small Amounts of Extra Cash?
Paid surveys, user tests, cash-back apps, and unclaimed property can pay small amounts that fit around your day. Think of them as pocket money for coffee, gifts, or a dinner out.
13. Join Paid Research Studies and Surveys
Market research firms pay for your opinions. Companies also pay testers to try websites and apps and talk through what they see. Expect a few dollars per survey and more for longer tests or interviews. Legitimate sites are free to join, so a sign-up fee is a red flag.
Cash-back apps and shopping portals return a share of what you spend, one of several passive income ideas for retirement.
14. Claim Money You Forgot About
States hold billions of dollars in unclaimed property: old bank accounts, uncashed checks, utility deposits, and insurance payouts. Search your name for free at MissingMoney.com, endorsed by the National Association of Unclaimed Property Administrators. Retirement accounts from old jobs can go missing too, and a lost 401(k) can be tracked down.
How Does Side Income Affect Social Security, Taxes, and Medicare?
Money you earn in retirement counts as income. It can reduce Social Security checks before full retirement age, raise your taxes, and push up Medicare premiums.
Social Security’s Earnings Limit
If you claim benefits before full retirement age, Social Security withholds $1 for every $2 you earn above $24,480 in 2026. The 2027 limit is $25,560. In the year you reach full retirement age, the limit rises to $65,160 ($67,920 in 2027), and $1 is withheld for every $3 above it. At full retirement age, your benefit goes up to credit the months that were withheld.
The limit counts wages and net self-employment earnings. Rental income, investment income, and money from selling your things don’t count.
Taxes on Side Income
Side income adds to your taxable income. It can also make more of your Social Security benefits taxable. Up to 85% becomes taxable once combined income passes $34,000 for single filers or $44,000 for joint filers.
If you freelance, consult, or run a small business, you’ll owe self-employment tax of 15.3% on most of your net self-employment earnings. No employer withholds it, so you may need to make quarterly estimated tax payments.
Medicare Premiums
Higher income can raise your Medicare Part B and Part D premiums through IRMAA. Medicare looks at your income from two years earlier, so 2026 premiums rest on 2024 income. In 2026, surcharges start above $109,000 for single filers and $218,000 for joint filers.
New Room to Save
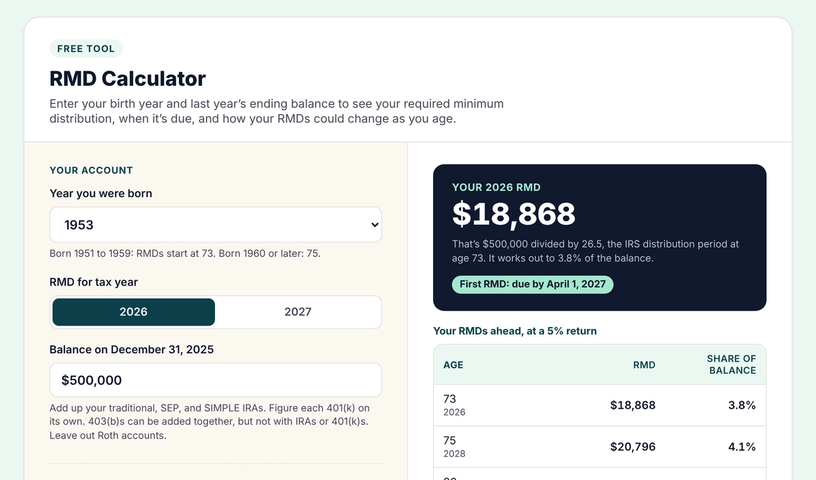
Earned income lets you keep contributing to an IRA at any age. In 2026 and 2027, you can put in up to $7,500, or $8,600 at 50 and older, but no more than you earn. Self-employed retirees can also open a solo 401(k) and save more.
How Much Can a Side Hustle Do for Your Retirement Plan?
A side hustle helps most when it covers spending you’d otherwise pull from savings. A steady $500 a month adds up to $6,000 a year. At a 4% withdrawal rate, replacing that income would take about $150,000 in savings.
Bigger amounts add up fast. A part-time job paying $2,000 a month from 62 to 67 covers $120,000 of spending, before counting growth on the savings you left invested. The same paycheck can let you wait to claim Social Security. With a full retirement age of 67, claiming at 67 pays about 43% more each month than claiming at 62.
Plans built on work income need a fallback. Nearly half of retirees in the EBRI/Greenwald survey stopped working earlier than they planned, often because of a health problem or changes at their company.
How Do You Choose the Right Side Hustle?
The right side hustle fits the money you need, the hours you want, and the kind of day you enjoy. Answer those three and the list gets short.
- Set an income target. Know the monthly amount you want and what it’s for, like travel, the years before Social Security, or a cushion for bad market years.
- Count your hours. Ten hours a week at $20 an hour brings in about $870 a month.
- Check startup costs. Licenses, equipment, insurance, and platform fees come out of what you earn.
- Watch for scams. Walk away from any job that asks you to pay up front or promises big pay for little work. Another warning sign is a check that arrives with a request to send part of it back. The FTC posts job scam alerts as new tricks appear.
- Try it before you count on it. Take a seasonal job or a few clients first. You’ll learn whether you like the work before your plan depends on the money.
How Can You Test Side Income in Your Plan?
Before you take on a side hustle, run the numbers. In the Boldin Planner, add part-time income for the years you expect to earn it. You’ll see how the paycheck changes your savings and taxes, and how it interacts with when you claim Social Security.
With PlannerPlus, you can save up to nine scenarios beside your baseline, then compare up to three side by side. Try one with the side income, one without, and one where the work stops early.
How to Make Money in Retirement: FAQ
What is the easiest way to make money in retirement?
The easiest ways to make money in retirement use something you already have. Selling things you don’t need, renting out storage space, and taking a seasonal job require little training. If you have professional skills, freelancing for former colleagues tends to pay the most for the least setup.
How much can I earn in retirement without losing Social Security?
Before full retirement age, Social Security withholds $1 for every $2 you earn above $24,480 in 2026, or $25,560 in 2027. In the year you reach full retirement age, it withholds $1 for every $3 above $65,160, or $67,920 in 2027. From full retirement age on, you can earn any amount.
Do I have to pay taxes on side hustle income in retirement?
Side hustle income is taxable at any age. Self-employed retirees also owe 15.3% self-employment tax on most net earnings. Extra income can make more of your Social Security benefit taxable, and a big enough increase can raise your Medicare premiums two years later.
What are good side hustles for seniors with no experience?
Good side hustles for seniors with no experience include pet sitting, retail and seasonal jobs, event staffing, driving, and paid surveys. Many employers train new hires. Selling unused items and renting out storage space need no experience at all.
How can a retiree make $1,000 a month?
A retiree can make $1,000 a month with about 12 hours of work a week at $20 an hour, or fewer hours of consulting at higher rates. Renting out a spare room can bring in that much in some areas. Two smaller sources, like pet sitting and selling unused items, can also get you there.