Baby boomers head about 31% of U.S. households but hold about half of all household wealth. That’s more than Gen X, millennials, and Gen Z combined. The median boomer household had a net worth of about $444,000 in 2025, according to Boldin’s analysis of the Federal Reserve’s 2025 Survey of Consumer Finances.
That number puts boomers at the top of generational wealth comparisons. It’s also the midpoint of a very wide spread. It doesn’t capture Social Security income or pension value, two assets that shape retirement security more than portfolio balance alone.
Where you land in that distribution, and how your assets convert to monthly income, matters more for your plan than the headline number. Here’s where boomer wealth came from, who it bypassed, and what the numbers look like when applied to your own situation.
Baby Boomers Entered Old Age Wealthier Than Any Generation Before Them
By the time baby boomers reached retirement age, they had accumulated more wealth than any previous generation, even after accounting for inflation. That’s according to Boldin’s analysis of the Federal Reserve’s Survey of Consumer Finances (SCF), the Fed’s main survey of household wealth.
The analysis holds age constant, comparing each generation’s median net worth at the same life stage (ages 61 to 79) in 2025 dollars. Those are the ages boomers were in 2025. A 2026 Pew Research Center analysis of the 2022 survey, using ages 58 to 76, found the same pattern.
| Generation | Ages at Measurement | Year Measured | Median Net Worth |
|---|---|---|---|
| Greatest Generation | 61 to 79 | 1989 | $219,900 |
| Silent Generation | 61 to 79 | 2007 | $364,900 |
| Baby Boomers | 61 to 79 | 2025 | $444,200 |
Source: Boldin analysis of Federal Reserve Survey of Consumer Finances public microdata (1989, 2007, and 2025 surveys). Median net worth of households headed by 61- to 79-year-olds, in 2025 dollars.
Boomers arrived 22% ahead of the Silent Generation at the same ages, with about twice the Greatest Generation’s median. The 2007 survey caught home values near their peak, which flatters the Silent Generation’s figure. If you built wealth through your working years, the data describes the conditions you moved through as much as the choices you made.
The Fed’s 2025 survey, released in October 2026, shows boomer wealth holding steady. After inflation, the median boomer household sits close to where the same generation stood in the 2022 survey.
The SCF doesn’t capture the present value of defined benefit pensions or projected Social Security income. For many boomers, those are two of the most important financial assets they have. Neither shows up in these net worth figures.
Baby Boomers Hold More Than Half of All U.S. Household Wealth
Baby boomers hold about $97 trillion in household wealth as of mid-2026, according to the Federal Reserve’s Distributional Financial Accounts (DFA). That’s about 52% of the U.S. total, though boomer households make up only about 31% of all households. More than 40% of boomer assets sit in stocks and 401(k)-style accounts, so the total rises and falls with the market.
| Generation | Share of U.S. Household Wealth | Approximate Total |
|---|---|---|
| Baby Boomers | ~52% | ~$97 trillion |
| Gen X | ~26% | ~$48 trillion |
| Millennials + Gen Z | ~11% | ~$21 trillion |
| Silent Generation and Older | ~11% | ~$20 trillion |
Source: Federal Reserve Distributional Financial Accounts, Q2 2026. Millennials + Gen Z covers everyone born in 1981 or later.
Boldin’s analysis of the 2025 survey puts the average boomer household’s net worth at about $1.9 million. The median is about $444,000.
That spread is telling: a small number of very high-net-worth households pull the average far above where most boomers land. The median reflects the middle of the distribution, which makes it the more useful benchmark for most households. In the same 2025 data, the top 10% of boomer households hold about 67% of the generation’s total wealth.
That concentration tracks with education. At every education level below a bachelor’s degree, boomers ended up with less wealth than their Silent Generation counterparts at the same ages. Only boomers with a bachelor’s degree or more came out ahead of the Silent Generation, and by about 4%.
| Education Level | Greatest Generation (1989) | Silent Generation (2007) | Baby Boomers (2025) |
|---|---|---|---|
| Less than HS diploma | $106,000 | $115,600 | $73,200 |
| HS diploma or GED | $227,500 | $236,800 | $230,300 |
| Some college or associate degree | $458,000 | $427,400 | $337,600 |
| Bachelor’s or higher | $873,000 | $1,154,500 | $1,198,900 |
Source: Boldin analysis of Federal Reserve Survey of Consumer Finances public microdata (1989, 2007, and 2025 surveys). Median net worth of households headed by 61- to 79-year-olds, by education of the household head, in 2025 dollars.
The median is where the typical boomer sits. But even $444,000 can fund a solid retirement or fall short, depending on how it’s structured and what the rest of the picture looks like. Retirement accounts are one piece of that picture. Here’s how much people your age have saved for retirement.
How Did Baby Boomers Get So Rich?
Boomers grew their wealth through a combination of real estate timing, decades of equity market exposure, and labor market conditions that are unlikely to repeat. Discipline and thrift alone don’t explain it.
Start with real estate. Boomers bought homes when prices were lower and held them through decades of sustained appreciation. About 80% of boomer households own their home, with a median of $290,000 in home equity among owners, according to Boldin’s analysis of the 2025 SCF. Geography and timing drove that run-up more than financial planning. If you bought in the 1970s or 1980s and held, that appreciation came to you by default.
Equity market exposure runs a close second. Boomers entered the workforce as 401(k) plans were expanding. Those who invested through their peak earning years benefited from one of the longest bull markets in modern history. Compounding over 30 to 40 years is a structural advantage that shorter time horizons can’t replicate.
Many boomers also have access to defined benefit pension plans that are now rare. Pension income doesn’t register in SCF net worth figures, but it supports retirement stability in a way that a portfolio alone has to work harder to replicate.
Then there’s the early-career drag that boomers avoided. Student debt burdens were smaller, and long-term employment was more stable. Both allowed wealth to compound sooner. Those starting conditions look different for the generations that followed.
Are Millennials Richer Than Boomers Were at Their Age?
Adjusted for inflation, millennials and Gen Z have more wealth on average than boomers did at the same life stage. That tends to get buried in the headlines.
St. Louis Fed analysis of U.S. household wealth finds that controlling for inflation, younger generations hold an average of about $1.35 for every $1 boomers held at an equivalent age. The dollar figures at the same life stage make that clearer than any ratio. Like any average, they lean toward the wealthiest households, so they say less about the typical one.
| Generation | Average Wealth at Age 34 (2024 dollars) |
|---|---|
| Baby Boomers (measured 1989) | $257,000 |
| Gen X (measured 2007) | $283,000 |
| Millennials + Gen Z (measured 2024) | $347,000 |
Source: St. Louis Fed, The State of U.S. Household Wealth, June 2025. All figures inflation-adjusted to 2024 dollars, compared at equivalent life stage (average age 34).
Decades of growth in boomer homes and portfolios outran what any generation can save from a paycheck.
Cerulli Associates estimates about $124 trillion will transfer from older Americans to younger generations through 2048, with boomers and older generations supplying nearly $100 trillion of that total.
The Median Boomer Net Worth Looks Solid Until You Run the Retirement Math
A median net worth of $444,000 sounds like a reasonable foundation. At a 4% withdrawal rate, it generates about $17,800 per year. For most households, that’s a supplement. Social Security covers the rest for most boomers, and for many, it’s the primary income source in retirement. It’s also not in the net worth figure, which makes $444,000 look more self-sufficient than it is.
Home equity creates the same problem, since it doesn’t convert to monthly income without selling, downsizing, or tapping a reverse mortgage. Net worth and liquid retirement assets are different numbers.
Start with the separation: calculate your net worth and break out liquid assets from home equity.
Model your Social Security timing before you claim. Claiming at 62 versus 70 can represent tens of thousands of dollars over a 20-year retirement. The right answer depends on your health, your other income sources, and your projected benefit.
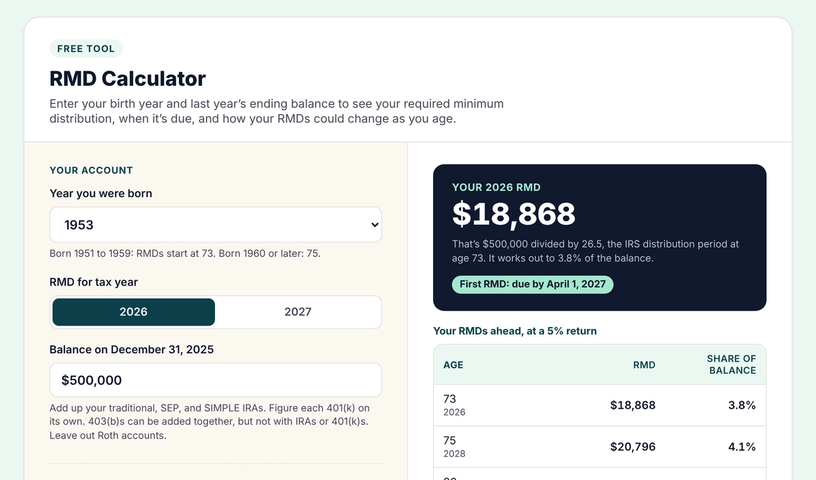
If you’re within 10 years of retirement, stress-test your withdrawal rate against a bad first decade. A plan that holds up under average conditions may have difficulty weathering sequence-of-returns risk. Finding the weak spots while you’re still working gives you time to fix them.
The Boldin Planner lets you run those stress scenarios against your specific numbers, including Social Security timing, withdrawal sequencing, and what a down decade early in retirement would cost you.
Frequently Asked Questions About Baby Boomer Net Worth
What is the average baby boomer net worth?
The average baby boomer household has a net worth of about $1.9 million, but the median is about $444,000, according to Boldin’s analysis of the Federal Reserve’s 2025 Survey of Consumer Finances. The top 10% of boomer households hold about 67% of all boomer wealth, which pulls the average far above where most boomers land.
How did baby boomers get so rich?
Boomer wealth accumulated through real estate appreciation, long-term equity market exposure, and access to defined benefit pension plans that are now rare. Boomers bought homes when prices were lower and held them through decades of appreciation, and their working years overlapped with a multi-decade equity bull market. Carrying less student debt than later generations also allowed wealth to compound and grow earlier.
Do baby boomers have more wealth than millennials?
As of mid-2026, boomers hold about $97 trillion, compared with about $21 trillion for millennials and Gen Z combined, according to Federal Reserve Distributional Financial Accounts data. Adjusted for inflation, though, millennials and Gen Z have more wealth on average at the same life stage than boomers did, according to the St. Louis Fed.
What percentage of U.S. wealth do baby boomers control?
Baby boomers control about 52% of total U.S. household wealth as of mid-2026, according to Federal Reserve Distributional Financial Accounts data. Boomer households make up about 31% of all U.S. households, according to Boldin’s analysis of the Fed’s 2025 Survey of Consumer Finances. That dominance comes from home equity and stock holdings accumulated over several decades of sustained appreciation.
Is $444,000 enough to retire on?
At a 4% withdrawal rate, $444,000 produces about $17,800 per year in portfolio income. For most people, that’s a supplement rather than a full retirement income. Most boomers depend on Social Security to cover much of their expenses, which is why Social Security timing, spending rate, and housing decisions matter as much as net worth when evaluating whether a retirement plan is funded.