Retiring alone means planning around one income, one Social Security check, and no spouse to step in when you need help. About 26% of Americans 65 and older lived alone in 2023, according to Pew Research Center. With a written plan, a few legal documents, and people you can count on, retiring alone can be secure and satisfying.
Sometimes it feels like the world is designed for couples. People throw dinner parties for couples, and most forms ask about your spouse. Facing retirement and aging on your own, at a stage when you’ll sometimes need a helping hand, can feel a little scary.
What Does No One Tell You About Retiring Alone?
No one tells you that retiring alone costs more per person, leaves you without a built-in caregiver, and puts every decision on you. It also gives you full control over where you live, how you spend, and how you fill your days.
- Your costs don’t get cut in half. Housing, utilities, and home and car insurance cost about the same for one person as for two, and one income pays for all of it.
- Taxes can rise after a spouse dies. You can file jointly for the year your spouse died. After that, most widows and widowers file as single, with narrower brackets and a smaller standard deduction.
- No one checks on you by default. If you fall or get sick, someone has to notice. Building that safety net is up to you.
- Living alone carries health risks. A 2015 analysis of mortality studies linked living alone to a 32% higher risk of early death and loneliness to a 26% higher risk.
- Every decision is yours. No one second-guesses where you live or when you claim Social Security, and no one catches your mistakes either.
- You have total freedom. You can move abroad, share a house with friends, or book a trip without negotiating with anyone.
Women are more likely than men to face this stage alone. In 2023, 31% of women 65 and older lived alone, compared with 19% of men, Pew found. A 2021 Census Bureau report counted 15.2 million adults 55 and older with no biological children as of 2018. Those without a spouse are sometimes called elder orphans or solo agers.
How Do You Plan Your Finances to Retire Alone?
To plan your finances for retiring alone, build a plan around one household, then add the backstops a spouse would otherwise provide. These four steps cover the money side.
1. Build a retirement plan for one
Retirement rules of thumb are built on averages, and they can carry a bias toward couples. A plan built on your own numbers shows what you spend, what income you’ll have, and how long your savings will last.
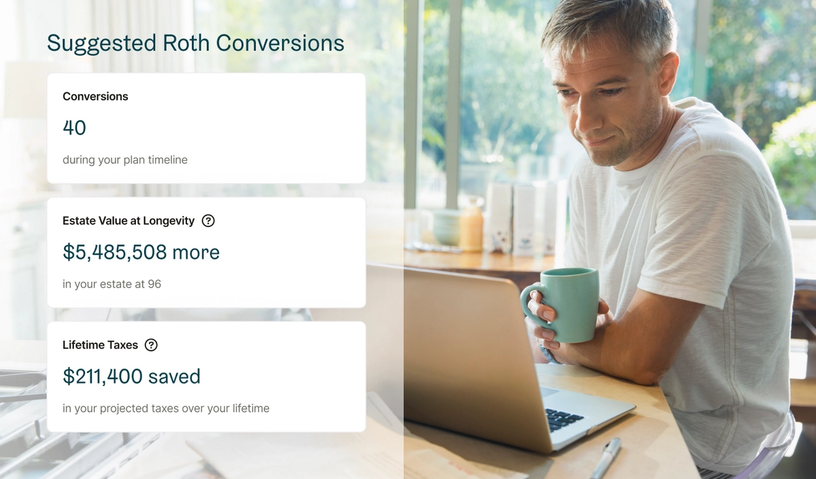
In the Boldin Planner, you enter your own income, savings, spending, and Social Security. It projects your taxes and cash flow year by year, so you can see whether your money lasts as long as you do. Financial worry runs high when you’re the only one responsible, and numbers you can check replace guesswork.
2. Pick your Social Security age with care
When you’re single, your own claiming age sets your income for life. Waiting from 62 to 70 raises your monthly benefit check by about 77% when your full retirement age is 67.
The Social Security Administration lets divorced people claim benefits on an ex-spouse’s record. The marriage must have lasted at least 10 years, and you must be unmarried and at least 62. You get whichever benefit is higher.
Widows and widowers have more room to plan. You can start one benefit, survivor or your own, and switch to the other later. The best order depends on your age and both benefit amounts.
3. Plan for long-term care before you need it
Someone turning 65 has almost a 70% chance of needing some long-term care, according to the Administration for Community Living. Many married people count on a spouse to help. When you’re single, you need to decide now who would help and how you’d pay.
Your options include savings, long-term care insurance, a hybrid policy, or other alternatives to long-term care insurance. You can add long-term care costs to your plan in the Boldin Planner and see how a care event would affect your savings.
4. Name your financial and healthcare proxies
A financial power of attorney names someone to manage your money if you can’t. A healthcare proxy names someone to make healthcare choices for you. Without these documents, a court may have to appoint a guardian.
An elder law attorney can draft the documents. For healthcare wishes, AARP offers free advance directive forms for every state, and you can also create an advance directive online. Name beneficiaries on every retirement account and insurance policy too.
Where Is the Best Place to Live When You Retire Alone?
The best place to live when you retire alone is close to people, services, and transportation you can use without a car.
5. Choose a walkable neighborhood
A walkable community keeps you connected to shops, doctors, and friends if you stop driving. Look for sidewalks, transit, and a grocery store you could reach on foot.
6. Share a home
Remember The Golden Girls? Living together with other single friends splits the costs and gives you company and help close at hand.
7. Look at retirement communities and villages
Retirement communities give you neighbors and activities on site, and some add care as you need it. A village is a neighborhood group whose members share services and social events while living in their own homes.
8. Consider a smaller home or a move abroad
Living alone, you might be happy in a tiny home. With no children or grandchildren nearby, living abroad can stretch your budget and open up a new adventure.
How Do You Stay Healthy and Connected When You Retire Alone?
Staying healthy and connected on your own takes a daily routine, people you see often, and someone who checks on you.
9. Keep a daily schedule
Work gave you a reason to get up and somewhere to be. Replace that structure with a schedule: a morning walk, a class, or a part-time job. Volunteering can give your week a sense of purpose.
10. Build a support network
Whether you’re an introvert or an extrovert, friendships matter to your health. You need people you can rely on for company and for practical help, and it helps to have people who rely on you too.
Set up a buddy system with friends for rides home from the doctor or the hospital. Better yet, create a chosen family: trusted friends, neighbors, or community members who act as your support system.
11. Stay social to protect your health
Feeling lonely is linked to a higher risk of heart disease and stroke. Being alone can feel great, but long stretches without contact can wear on your health.
The Elder Orphans Facebook group connects people over 55 who don’t have a spouse or nearby children. Want a group closer to home? Start your own club with single friends near retirement age and meet weekly or monthly.
12. Set up regular check-ins
Pick a friend, relative, or neighbor to check in with on a set schedule. Tell them what worries you, such as a fall or memory changes, and what you’d want them to do.
If no one fits that role, an aging life care professional can act as a paid advocate and coordinate your care.
13. Get a medical alert device
A medical alert device calls for help if you fall and can’t reach a phone. Some detect falls on their own.
14. Consider a pet
A dog gets you outside for a walk every day and keeps you company at home. Pets have been linked to better heart health and less loneliness. Plan for who would care for your pet if you couldn’t.
15. Travel solo
Solo travel gets easier with the right outfitter. Retirement travel can stay affordable with off-season dates and small-group tours. These companies run trips for older solo travelers:
What If You Become Single After Retirement?
If you become single after retirement, start by learning where everything stands: accounts, bills, insurance, and benefits. Divorce and the death of a spouse both leave one person managing money that two once shared.
At 65, my grandmother had not paid a bill in her entire life. My grandfather handled all the finances. When he developed Alzheimer’s, she stepped into the role of financial manager without hesitating. She even knew enough to hire a fee-only financial advisor to help with their investments.
Income can drop too. When a spouse dies, the household keeps the larger of the two Social Security checks and loses the smaller one. A gray divorce splits savings that were meant to support one household.
If you’re married, learn how your money works now. A written retirement plan shows what each of you would have to live on alone.
Retiring Alone: FAQ
What is a solo ager?
A solo ager is an older adult who lives without a spouse or partner and has no adult children nearby to help. The term covers people who stayed single, divorced, or were widowed. Many prefer it to “elder orphan,” an older label for the same group of aging adults.
How much money do you need to retire alone?
The money you need to retire alone depends on your spending, your Social Security benefit, and how many years your money has to cover. Start from your yearly budget and subtract guaranteed income such as Social Security or a pension. Plan for the gap to last into your 90s, and add a reserve for long-term care.
Who makes medical decisions for you if you live alone?
Medical decisions for someone who lives alone fall to the healthcare proxy named in an advance directive. Without one, state law sets who decides, which may be a distant relative, and a court may step in. Naming a proxy you trust, and telling them your wishes, keeps that choice in your hands.
Can a widow collect survivor benefits and switch later?
A widow or widower can start Social Security survivor benefits as early as 60. If their own retirement benefit will pay more, they can switch to it as late as 70. The survivor benefit covers the early years while their own benefit keeps growing. Comparing both amounts at each age shows which order pays more.
How do solo seniors avoid loneliness?
Solo seniors avoid loneliness by building regular contact into their week. A standing coffee date, a walking group, a faith community, or a hobby class all help. Shared housing and village networks add daily contact. Online groups can fill the gaps between visits with people who know you.